The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Shop insurance premiums can vary widely because insurers assess both your retail business and the cover you choose. This guide explains common cost factors, from business type and location to stock value, claims history, policy limits and economic conditions.
The cost of shop insurance in Australia can vary from one retail business to another, even when two stores appear similar from the outside. Insurers generally look at the type of business you operate, where you trade, what you sell, the value of your stock and fit-out, your claims history, the covers you select and broader market conditions.
This article explains common shop insurance cost factors so you can better understand why premiums differ and what information may be requested when you seek shop insurance quotes. It is general information only and does not take into account your business objectives, financial situation or insurance needs.
Why shop insurance premiums vary
Retail shop insurance is not usually priced as a flat fee for every business. A small clothing boutique, a suburban bakery, a jeweller, a convenience store and an online retailer with a stockroom can all have different risk profiles.
When assessing a quote, an insurer may consider the likelihood of a claim, the possible size of a claim and the cost of providing the selected cover. A business that has higher-value stock, greater customer foot traffic, specialised equipment or a history of claims may be assessed differently from a lower-risk retail operation.
Premiums can also change over time. If your business grows, moves premises, adds online sales, increases stock levels or changes the types of products it sells, your insurance needs and pricing may change as well.
Business factors that can influence shop insurance cost
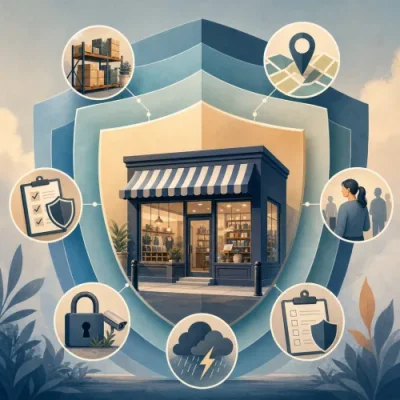
The details of your business are central to how insurers assess risk. The following factors commonly influence retail insurance premiums, although the weighting of each factor depends on the insurer and policy.
| Factor |
Why it may affect the premium |
| Type of retail business |
Different shops face different risks. For example, food retailers, electronics stores, clothing shops and jewellery stores may have different liability, theft, spoilage or stock risks. |
| Annual turnover |
Turnover can indicate the scale of operations, customer activity and potential exposure to claims. |
| Location |
Insurers may consider local crime risk, weather exposure, flood or storm risk, building surroundings and access to emergency services. |
| Stock value |
Higher stock values can increase the potential cost of a fire, theft, water damage or other insured event. |
| Fit-out and equipment |
Specialised shelving, refrigeration, counters, signage, machinery or point-of-sale systems may increase replacement costs. |
| Claims history |
Previous claims may be considered when assessing the likelihood of future claims, depending on the circumstances. |
| Security and risk controls |
Alarms, locks, shutters, cameras, fire protection and safe storage practices may be relevant to the insurer's assessment. |
Business type and products sold
The nature of your retail business can make a significant difference to the cost of cover. A gift shop selling low-value general merchandise may be assessed differently from a business selling high-value electronics, jewellery, alcohol, beauty products or perishable food.
Some products may increase the potential for certain types of claims. For example:
- food and beverage retailers may need to consider spoilage, contamination or equipment breakdown risks;
- stores selling higher-value stock may face greater theft or burglary exposure;
- retailers selling goods that could cause injury or damage may need to consider product liability exposure;
- businesses with online sales may need to think about cyber, transit and warehousing risks.
If your business changes what it sells, imports new product lines or expands into e-commerce, it is worth checking whether your existing policy still reflects your operations.
Turnover, customer traffic and business size
Turnover is commonly used as a measure of business scale. Higher turnover can suggest more transactions, more customers and greater potential exposure to liability claims. It can also indicate higher stock movement and potentially higher business interruption exposure.
Customer traffic may also be relevant. A busy shopfront with frequent visitors, narrow aisles, displays, stairs or wet areas may present different public liability risks from a business with limited in-person customer interaction.
Business size can include more than revenue. Insurers may also consider the number of locations, employees, trading hours, delivery activities and whether you operate from a leased shop, market stall, home-based storage area or warehouse.
Location and premises risk
Where your shop operates can influence your premium. Insurers may consider localised risks such as break-ins, vandalism, storm, flood, bushfire, cyclone or other weather-related exposures. These factors can vary significantly across Australia.
The physical premises can matter too. A shop in a modern building with strong fire protection may be assessed differently from one in an older building with ageing electrical systems or limited security. If you lease your premises, your lease may also set out responsibilities for glass, fixtures, fit-out, liability or other insurance-related obligations.
Insurers may ask about:
- the construction materials of the building;
- the age and condition of the premises;
- whether the shop is in a shopping centre, strip retail area or standalone building;
- neighbouring businesses and shared walls;
- fire alarms, sprinklers and extinguishers;
- security systems, locks, shutters and safes.
Stock value, fit-out and equipment
Property-related covers are often influenced by the value of what needs to be repaired or replaced after an insured event. For a retailer, this may include stock, shelving, display units, counters, refrigeration, computers, tools, signage and other business contents.
Underestimating these values may reduce your premium in the short term, but it can leave the business exposed if a claim occurs and the insured amount is not enough. Overestimating values may mean paying for cover that does not reflect your actual exposure. The appropriate insured amount depends on your circumstances, policy terms and provider criteria.
Seasonal businesses should also think carefully about stock fluctuations. A retailer may hold significantly more stock before Christmas, Easter, major sale periods or local events. Some policies may allow for seasonal increases, but this depends on the insurer and policy wording.
Claims history and risk management
Your claims history can be one of the factors insurers consider when pricing shop insurance. A single claim does not necessarily mean a business will be treated as high risk, but repeated or severe claims may affect premium, excess, cover terms or availability.
Risk management can also influence how your business is viewed. While no measure can remove risk entirely, insurers may ask whether you have practical controls in place, such as:
- regular electrical and equipment maintenance;
- clear cleaning and spill-response procedures;
- staff training for customer safety and manual handling;
- secure storage for cash or high-value goods;
- documented opening and closing procedures;
- fire safety checks and emergency plans.
Good records can help when discussing your risk profile with an insurer or broker, particularly if your business has made improvements after a previous incident.
Policy choices that affect your premium
The cost of shop insurance is not only about the business itself. It also depends on the policy structure and the covers you choose. Two quotes may look similar at first glance but provide different limits, exclusions, excesses and optional benefits.
Types of cover selected
A retail insurance package may include several types of cover, such as public liability, property, theft, glass, business interruption, money, equipment breakdown, product liability or cyber insurance. The more extensive the cover, the more the premium may be affected.
For an overview of common cover types, you may wish to read the guide to essential insurance types for e-commerce and physical store owners.
Coverage limits
Policy limits set the maximum amount the insurer may pay for a particular type of claim, subject to the policy terms, exclusions and conditions. Higher limits generally increase the insurer's potential exposure, which may affect the premium.
It is important to consider whether a limit is appropriate for the risk being insured. For example, a business with high-value stock or a costly fit-out may need to think carefully about property limits. A business with significant customer traffic may need to consider its public liability limit. The right level of cover depends on the business, contract requirements, lease obligations and insurer criteria.
Excess levels
The excess is the amount you may need to contribute towards a claim. Choosing a higher excess may reduce the premium in some cases, but it also means the business carries more of the cost if a claim occurs. Choosing a lower excess may increase the premium but reduce out-of-pocket costs at claim time.
This trade-off should be considered carefully. A higher excess may not be suitable if it would create cash flow pressure after an incident.
Optional benefits and extensions
Optional extras can provide useful protection, but they may also increase the premium. Examples can include cover for goods in transit, machinery breakdown, tax audit, cyber events, employee dishonesty or expanded business interruption benefits.
Policy wording matters. Similar-sounding optional covers can differ between insurers, so it is worth checking definitions, limits, waiting periods, exclusions and claim conditions before comparing price alone.
Public liability premium factors for retailers
Public liability insurance is commonly considered by retail businesses because customers, suppliers, couriers and other visitors may enter the premises. A public liability premium may be influenced by the type of shop, foot traffic, premises layout, products sold, trading activities and selected limit.
Examples of factors that may be relevant include:
- whether customers handle products, use change rooms or move through narrow aisles;
- whether the shop has steps, ramps, outdoor displays or shared walkways;
- whether food, cosmetics, electrical items or other higher-exposure goods are sold;
- whether the business attends markets, pop-up events or trade shows;
- whether leases, suppliers or contracts require a particular liability limit.
Public liability cover is not the same as cover for your own stock, contents or lost income. Retailers often need to consider liability and property risks together rather than focusing on one type of cover in isolation.
Economic shifts can also affect shop insurance premiums
The original focus of this article was the impact of economic shifts on retail insurance premiums, and that remains an important part of the cost picture. Even if your individual business has not changed, broader market conditions can affect the price and availability of insurance.
Economic shifts refer to changes in the wider business environment, such as inflation, interest rate movements, changes in supply chains, currency fluctuations, labour costs and changes in the cost of building materials or replacement goods. These can influence insurers because they affect the cost and frequency of claims.
For example, if replacement stock, building repairs or specialist equipment become more expensive, insurers may face higher claim costs. This can flow through to premiums across parts of the market. Weather events, reinsurance costs and changes in the frequency or severity of claims can also contribute to pricing pressure.
Retailers should be careful not to assume that a premium change is caused by one factor only. An increase could reflect a combination of your business details, claims experience, cover changes and broader market conditions.
Information you may need for a shop insurance quote
Preparing accurate information can make the quote process smoother and help reduce the risk of misunderstandings. Depending on the insurer, broker or platform, you may be asked for details such as:
- business name, ABN and trading activities;
- shop address and premises type;
- annual turnover and number of employees;
- types of products sold and whether you import or manufacture goods;
- stock value, contents value and fit-out value;
- security measures and fire protection;
- claims history;
- current insurance details, if any;
- preferred limits, excesses and optional covers.
Online tools can help you organise estimates and compare assumptions before requesting cover. If useful, you can explore the site's business insurance calculators to support your planning, noting that calculators are general tools and do not determine the final premium an insurer may offer.
How to compare shop insurance quotes beyond price
Cost matters, especially for small retailers managing tight margins. However, the cheapest-looking option is not necessarily the most appropriate. A lower premium may reflect lower limits, higher excesses, narrower cover or exclusions that are important to your business.
When comparing shop insurance policies, consider:
- what is covered: check whether the policy includes the risks most relevant to your store;
- what is excluded: exclusions can significantly affect whether a claim is payable;
- policy limits: confirm whether the insured amounts are realistic for your stock, fit-out and liability exposure;
- excesses: understand what you would need to pay if you claimed;
- waiting periods: these may apply to some business interruption or other covers;
- claims conditions: check notification, documentation and maintenance requirements;
- optional covers: decide whether add-ons are necessary for your operations.
If your business has multiple locations, high-value stock, unusual products, prior claims, contractual insurance requirements or complex risks, speaking with an insurance broker may help you understand available options. You can learn more through the site's broker information.
Ways to manage premiums without leaving major gaps
There is no guaranteed way to reduce shop insurance premiums, and any pricing outcome depends on your circumstances and insurer criteria. However, there are practical steps that may help you manage costs while keeping cover aligned with your business risks.
- Review insured values regularly: update stock, contents and fit-out values so they reflect your current business.
- Check cover you no longer need: remove or adjust cover that no longer matches your operations, if appropriate.
- Consider excess options carefully: a higher excess may reduce premiums in some cases, but only if the business can afford it at claim time.
- Improve risk controls: security, maintenance, fire safety and staff procedures may support a stronger risk profile.
- Keep claims records: document incidents, repairs and improvements after claims.
- Compare policy terms, not just price: similar premiums can provide very different levels of protection.
- Review after business changes: reassess cover when you move, renovate, expand, add online sales or change products.
For more detail on timing and process, see the guide to regularly reviewing your shop insurance coverage.
Key takeaways for Australian retailers
Shop insurance cost is shaped by both your business risk profile and your policy choices. Factors such as business type, turnover, location, stock value, fit-out, claims history, limits, excesses, optional covers and economic conditions can all influence premiums.
The most useful approach is to prepare accurate business information, understand what each policy includes and review cover when your circumstances change. Premiums, cover availability and policy terms depend on the insurer's criteria and your individual business details, so it is worth asking questions before relying on price alone.
Published: Monday, 13th Apr 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.